

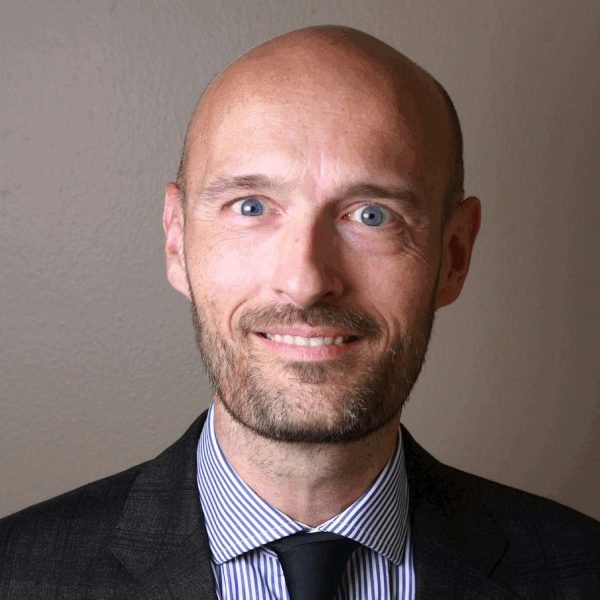
Patrick Boyle
- Episodes
- 381
- Released
- daily
- Latest episode
- Nov 14, 2026
About the podcast
Patrick Boyle is a hedge fund manager, a university professor and a former investment banker. This channel is all about quantitative finance. By subscribing you will see videos explaining what is happening in markets right now, you will learn about financial derivatives, corporate finance and how traders use quantitative tools like statistics. You will see interviews with some of the most interesting people in the financial industry. In addition, you will see some longer form documentaries on the history of financial markets.To contact Patrick go to the website http://onfinance.orgDISCLAIMER:This channel is not affiliated with any financial institution. The videos on this channel are for entertainment purposes only and do not constitute financial advice. Those seeking investment advice should seek out a registered professional. Patrick is not responsible for investment actions taken by viewers and his content should not be used as a basis for investment.Links:Amazon Author Page: https://amzn.to/3bTeqedPatreon: https://www.patreon.com/PatrickBoyleOnFinanceWebsite: https://www.onfinance.org/Instagram: https://www.instagram.com/patrickeboyle/BlueSky: https://bsky.app/profile/pboyle.bsky.social
Episodes 381
What are the Option Greeks? | Hedging Options | Risk Managing Options
These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0 Check out our website http://www.onfinance.org/Follow Patrick on …
Show notes
These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0
Check out our website http://www.onfinance.org/
Follow Patrick on twitter here: https://twitter.com/PatrickEBoyle
If you're an options investor, you may have heard about "Greeks" but you may not know exactly what they are or what they can do for you. If so, watch this series of videos where Patrick Boyle explains what these Greek letters mean and how to use them to better understand the price of an option.
What can option Greeks do for you?
Using the Greeks, an options investor can make more informed decisions about which options to trade, and when to trade them. Consider some of the things Greeks may help you do:
Gauge the likelihood that an option you're considering will expire in the money (Delta).
Estimate how much the Delta will change when the stock price changes (Gamma).
Get a feel for how much value your option might lose each day as it approaches expiration (Theta).
Understand how sensitive an option might be to large price swings in the underlying stock (Vega).
Simulate the effect of interest rate changes on an option (Rho).
What are Greeks anyway?
Greeks, including Delta, Gamma, Theta, Vega and Rho, measure the different factors that affect the price of an option contract. They are calculated using a theoretical options pricing model (see How much is an option worth?).
Since there are a variety of market factors that can affect the price of an option in some way, assuming all other factors remain unchanged, we can use these pricing models to calculate the Greeks and determine the impact of each factor when its value changes. For example, if we know that an option typically moves less than the underlying stock, we can use Delta to determine how much it is expected to move when the stock moves $1. If we know that an option loses value over time, we can use Theta to approximate how much value it loses each day.
what is delta gamma theta vega in optionsLearn more about your ad choices. Visit megaphone.fm/adchoices
What is Put Call Parity? How does it work?
Today we will learn about put call parity and how it works,These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0 Check out …
Show notes
Today we will learn about put call parity and how it works,
These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0
Check out our website http://www.onfinance.org/
Follow Patrick on twitter here: https://twitter.com/PatrickEBoyle
What is Put-Call Parity
Put-call parity is a no arbitrage principle that specifies the relationship between the price of European put options and European call options, with the same underlying asset, strike price and expiration date. Put-call parity states that simultaneously holding a short European put and long European call of the same class will deliver the same return as holding one forward (or futures) contract on the same underlying asset, with the same expiration, and a forward price equal to the option's strike price. If the prices of the put and call options diverge so that this relationship does not hold, an arbitrage opportunity would exist, meaning that arbitrage traders would be able to earn a risk-free profit. Such opportunities are uncommon and short-lived in liquid markets.
The equation expressing put-call parity is:
C + PV(x) = P + S
where:
C = price of the European call option
PV(x) = the present value of the strike price (x), discounted from the value on the expiration date at the risk-free rate
P = price of the European put
S = spot price or the current market value of the underlying asset
Put-call parity applies only to European options, which can only be exercised on the expiration date, and not American options, which can be exercised before.
Watch Patrick's other videos on covered calls and protective puts to better understand this concept.
Covered Call Video: https://www.youtube.com/watch?v=UlC9iM2Wh7I
Protective Put Video: https://www.youtube.com/watch?v=MUs4jga-NAI&t=26s
What is Put Call Parity? How does it work? put call parity formulaLearn more about your ad choices. Visit megaphone.fm/adchoices
What are forward rates? What are forward rate agreements? What is an FRA?
In todays video we will learn about forward interest rates and a derivative called a forward rate agreement or FRA.These classes are all based on the book Trading and Pricing Financial Derivatives, available on …
Show notes
In todays video we will learn about forward interest rates and a derivative called a forward rate agreement or FRA.
These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0
Check out our website http://www.onfinance.org/
Follow Patrick on twitter here: https://twitter.com/PatrickEBoyle
What are Forward Rates?
A forward rate is an interest rate implied for periods of time in the future by zero-coupon bonds. For example, the market implied yield on a three-month Treasury bill three months from now is a forward rate.
If we know what the three-month zero-coupon Treasury bill rate is and what the six-month zero-coupon Treasury bill rate is, we can back out what the market is implying as the yield on a three-month Treasury bill three months from now.
To calculate forward rates we just need the zero-coupon yield curve.
What are Forward Rate Agreements?
A forward rate agreement (FRA) is an over-the-counter agreement to borrow a fixed amount of money at a fixed interest rate at a specified future time period.
Banks and large corporations can use FRAs to hedge future interest rate exposures. The buyer hedges against the risk of rising interest rates, while the seller hedges against the risk of falling interest rates. Speculators can use FRAs to make bets on future changes in interest rates.
Rates in the future will usually be different from the implied rate at the time you entered into a forward-rate-agreement, giving rise to gains or losses on the agreed transaction.
What is an FRA?
An FRA is an abbreviated term for Forward Rate AgreementLearn more about your ad choices. Visit megaphone.fm/adchoices
How The War in Ukraine Will Affect Third World Food Prices
Learn more about your ad choices. Visit megaphone.fm/adchoices
Pfizer CEO Sells Shares After Vaccine Announcement - What Does It Mean?
Learn more about your ad choices. Visit megaphone.fm/adchoices
Creating Neutral Portfolios - The Option Greeks
These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0 Check out our website http://www.onfinance.org/Follow Patrick on …
Show notes
These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0
Check out our website http://www.onfinance.org/
Follow Patrick on twitter here: https://twitter.com/PatrickEBoyle
The option sensitivity measures familiar to most option traders are often referred to as the Greeks: delta, gamma, vega, lambda, rho, and theta. Delta is the price sensitivity of an option with respect to changes in the price of the underlying asset. It represents a first-order sensitivity measure analogous to duration in fixed income markets. Gamma is the sensitivity of an option's delta to changes in the price of the underlying asset, and represents a second-order price sensitivity analogous to convexity in fixed income markets. Vega is the price sensitivity of an option with respect to changes in the volatility of the underlying asset. See Pricing and Analyzing Equity Derivatives or the Glossary for other definitions.
The Greeks of a particular option are a function of the model used to price the option. However, given enough different options to work with, a trader can construct a portfolio with any desired values for its greeks. For example, to insulate the value of an option portfolio from small changes in the price of the underlying asset, one trader might construct an option portfolio whose delta is zero. Such a portfolio is then said to be “delta neutral.” Another trader may want to protect an option portfolio from larger changes in the price of the underlying asset, and so might construct a portfolio whose delta and gamma are both zero. Such a portfolio is both delta and gamma neutral. A third trader may want to construct a portfolio insulated from small changes in the volatility of the underlying asset in addition to delta and gamma neutrality. Such a portfolio is then delta, gamma, and vega neutral.Learn more about your ad choices. Visit megaphone.fm/adchoices
What are Variance Swaps? Financial Derivatives - Trading Volatility
In todays video we learn about variance swapsThese classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0 Check out our website …
Show notes
In todays video we learn about variance swaps
These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0
Check out our website http://www.onfinance.org/
Follow Patrick on twitter here: https://twitter.com/PatrickEBoyle
What is a Variance Swap?
A variance swap is a financial derivative used to hedge or speculate on the magnitude of a price movement of an underlying asset.
A variance swap is a forward contract with a payoff based on the realized variance of the underlying asset. Variance swaps settle in cash based on the difference between the realized variance and the variance strike
Similar to a regular swap, one of the two parties involved in the transaction will pay an amount based upon the actual variance of price changes of the underlying asset. The other party will pay a fixed amount, called the strike, specified at the start of the contract. The strike is typically set at the start to make the net present value of the payoff zero.
At the end of the contract, the net payoff to the counterparties will be the notional amount multiplied by the difference between the variance and the strike variance, settled in cash. Due to any margin requirements specified in the contract, some payments may occur during the life of the contract should the contract's value move beyond the agreed limits.
The variance swap, in mathematical terms, is the arithmetic average of the squared differences from the mean value. The square root of the variance is the standard deviation.
A variance swap is a pure-play on an underlying asset's volatility. Options also give an investor the possibility to speculate on an asset's volatility. But, options carry directional risk, and their prices depend on many factors.
There are two main classes of users for variance swaps.
Speculators use these swaps to speculate on the future level of volatility for an asset.
Hedgers use variance swaps to cover short volatility positions.
They are similar to volatility swaps, watch my video on those here. https://www.youtube.com/watch?v=qclLj3E5zykLearn more about your ad choices. Visit megaphone.fm/adchoices
How Did Russian Oligarchs Get So Rich?
Learn more about your ad choices. Visit megaphone.fm/adchoices
Applied Portfolio Management - Class 1 - Risk and Return
All slides are available on my Patreon page: https://www.patreon.com/PatrickBoyleOnFinanceBook Suggestions:Burton Malkiel, A Random Walk Down Wall Street (2007) https://amzn.to/2Hr2SW1Roger Lowenstein, Buffett …
Show notes
All slides are available on my Patreon page: https://www.patreon.com/PatrickBoyleOnFinance
Book Suggestions:
Burton Malkiel, A Random Walk Down Wall Street (2007) https://amzn.to/2Hr2SW1
Roger Lowenstein, Buffett: The Making of an American Capitalist (2008) https://amzn.to/3hUkFl6
Jack Schwager, Market Wizards Series https://amzn.to/3a89diH
Jack Schwager, Market Sense And Nonsense (2013) https://amzn.to/3jerS0Z
Nassim Nicholas Taleb, Fooled By Randomness (2007) https://amzn.to/365wN08
Victor Niederhoffer, Education of a Speculator (1998) https://amzn.to/2EuhMJZ
Victor Niederhoffer, Practical Speculation (2004) https://amzn.to/2Hr3nzn
Dimson, E., Marsh, P., and M. Staunton, Triumph of the Optimists: 101 Years of Global Investment Returns (2002) https://amzn.to/363JWXG
Roger Lowenstein, When Genius Failed (2001) https://amzn.to/364aHv7
Ivan Boesky, Merger Mania (1985) https://amzn.to/3crKszQ
Howard Marks, The Most Important Thing (2011) https://amzn.to/30n89EX
Frank Partnoy, F.I.A.S.C.O. (1999) https://amzn.to/366gGj4
Michael Lewis, Liars Poker (1989) - The Big Short (2010) https://amzn.to/3mPjhE1
Gregory Zuckerman, The Man Who Solved the Market (2019) https://amzn.to/2FVOZi8
Patricks' Books:
Statistics for Traders: https://amzn.to/3eerLA0
Financial Derivatives: https://amzn.to/307ByTb
Corporate Finance: https://amzn.to/3fn3rvC
Visit our website: www.onfinance.org
Follow Patrick on Twitter Here: https://twitter.com/PatrickEBoyle
Risk & Return in Finance.
The higher the risk taken, the more greater the expected return should be, and conversely, the lower the risk, the more modest the expected return. In this class we learn about how traders and portfolio managers think about risk and return. We learn about indifference curves, diversification and the importance of correlation in building a portfolio. We learn about sharpe ratio, sortino ratio and beta.
Often people are confused by the idea of the risk return tradeoff. They think that taking a higher risk means that you are guaranteed a higher return. Of course, if this was the case, risk would not be risky. In finance what the risk return tradeoff is referring to is the idea that an investor would only agree to take greater risk, if they believed that the positive outcomes were greater than the positive outcomes achieved for low risk investments.Learn more about your ad choices. Visit megaphone.fm/adchoices
What Happens To Sanctioned Oligarchs' Assets?
Learn more about your ad choices. Visit megaphone.fm/adchoices
Introduction to Derivatives - Futures and Forwards - Revision Class1
A revision slideshow on Futures and Forwards.These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0 Check out our website …
Show notes
A revision slideshow on Futures and Forwards.
These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0
Check out our website http://www.onfinance.org/
Follow Patrick on twitter here: https://twitter.com/PatrickEBoyleLearn more about your ad choices. Visit megaphone.fm/adchoices
What is Backwardation and Contango in Futures Markets?
What is Backwardation and Contango in Futures Markets?These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0 Check out our …
Show notes
What is Backwardation and Contango in Futures Markets?
These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0
Check out our website http://www.onfinance.org/
Follow Patrick on twitter here: https://twitter.com/PatrickEBoyle
Contango and backwardation are terms often used within commodity circles. These terms refer to the shape of the futures curve of a commodity such as gold, silver, wheat or crude oil. A futures curve can be plotted on a chart of a particular contract by using an X and Y axis. The X axis contains the various contract expiration dates while the Y axis contains the corresponding futures prices. A normal futures curve will show a rising slope as the prices of futures contracts rises in time. An inverted futures curve will show a falling slope as the prices of futures contracts falls over time.
A contango market simply means that the futures contracts are trading at a premium to the spot price. For example, if the price of a crude oil contract today is $100 per barrel, but the price for delivery in six months is $110 per barrel, that market would be in contango. On the other hand, if crude oil is trading at $100 per barrel for delivery right now, and the six month contract is trading at $95 per barrel, then that market would be said to be in backwardation.
Contango and backwardation are curve structures seen in futures markets based on several factors. It is important to remember that the futures price eventually converges on the spot price. In other words, any gaps between the futures price and the spot price will close as contract expiration nears.
The shape of the futures curve is important to commodity hedgers and speculators. Both care about whether commodity futures markets are contango markets or normal backwardation markets. In 1993, the German company Metallgesellschaft famously lost more than $1 billion dollars, mostly because management deployed a hedging system that profited from normal backwardation markets but did not anticipate a shift to contango markets.Learn more about your ad choices. Visit megaphone.fm/adchoices
Commercial Real Estate Meltdown?
Start speaking a new language in 3 weeks with Babbel 🎉. Get up to 60% OFF your subscription ➡Here: https://go.babbel.com/t?bsc=1200m60-youtube-patrickboyle-may-2023&btp=default&utm_term=generic_v1&utm_medium=pai …
Show notes
Start speaking a new language in 3 weeks with Babbel 🎉. Get up to 60% OFF your subscription ➡Here: https://go.babbel.com/t?bsc=1200m60-youtube-patrickboyle-may-2023&btp=default&utm_term=generic_v1&utm_medium=paidsocial&utm_source=YouTube&utm_content=Influencer..patrickboyle..USA..YouTube
The next big potential risk to the U.S. economy may be lurking in office buildings across the country's downtown districts.
With many people still working from home, companies are cutting back on office space which threatens to unleash even more headwinds for the U.S. economy.
Patrick's Books:
Statistics For The Trading Floor: https://amzn.to/3eerLA0
Derivatives For The Trading Floor: https://amzn.to/3cjsyPF
Corporate Finance: https://amzn.to/3fn3rvC
Patreon Page: https://www.patreon.com/PatrickBoyleOnFinance
Visit our website: www.onfinance.org
Follow Patrick on Twitter Here: https://twitter.com/PatrickEBoyle
Patrick Boyle On Finance Podcast:
Spotify: https://open.spotify.com/show/7uhrWlDvxzy9hLoW0EYf0b
Apple: https://podcasts.apple.com/us/podcast/patrick-boyle-on-finance/id1547740313
Google Podcasts: https://tinyurl.com/62862nve
Join this channel to support making this content:
https://www.youtube.com/channel/UCASM0cgfkJxQ1ICmRilfHLw/joinLearn more about your ad choices. Visit megaphone.fm/adchoices
Will The West Ban Russian Oil Imports?
Learn more about your ad choices. Visit megaphone.fm/adchoices
Trump’s $2B Chip Deal: Nvidia’s Big Payout Explained
Go to https://ground.news/pb to get up to 40% off unlimited access to stay fully informed. Subscribe through my link this month for 40% off unlimited access.In this deep dive, we unpack Donald Trump’s …
Show notes
Go to https://ground.news/pb to get up to 40% off unlimited access to stay fully informed. Subscribe through my link this month for 40% off unlimited access.
In this deep dive, we unpack Donald Trump’s controversial deal with Nvidia and AMD — a 15% revenue-sharing arrangement that allows U.S. AI chips to be exported to China. Is this a clever geopolitical strategy or a dangerous precedent that monetizes national security?
We explore:
How the deal was brokered and what it means for U.S. trade policy
Legal and constitutional concerns surrounding export controls
Strategic risks of enabling China’s AI development
Comparisons to China’s rare earth leverage and Xi Jinping’s CEO control
The broader pattern of Trump’s executive interference in private enterprise
Featuring analysis on the H20 chip, inference bottlenecks, golden shares, and the future of American capitalism.
Patrick's Books:
Statistics For The Trading Floor: https://amzn.to/3eerLA0
Derivatives For The Trading Floor: https://amzn.to/3cjsyPF
Corporate Finance: https://amzn.to/3fn3rvC
Ways To Support The Channel
Patreon: https://www.patreon.com/PatrickBoyleOnFinance
Buy Me a Coffee: https://www.buymeacoffee.com/patrickboyle
Visit our website: https://www.onfinance.org
Follow Patrick on Twitter Here: https://bsky.app/profile/pboyle.bsky.social
Business Inquiries ➡️ [email protected]
Patrick Boyle On Finance Podcast:
Spotify: https://open.spotify.com/show/7uhrWlDvxzy9hLoW0EYf0b
Apple: https://podcasts.apple.com/us/podcast/patrick-boyle-on-finance/id1547740313
Google Podcasts: https://tinyurl.com/62862nve
Join this channel to support making this content:
https://www.youtube.com/channel/UCASM0cgfkJxQ1ICmRilfHLw/joinLearn more about your ad choices. Visit megaphone.fm/adchoices
What is a Protective Put? Options Trading Strategies
These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0 Check out our website http://www.onfinance.org/Follow Patrick on …
Show notes
These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0
Check out our website http://www.onfinance.org/
Follow Patrick on twitter here: https://twitter.com/PatrickEBoyle
What is a Protective Put?
A protective put is a trading or investment strategy that investors can use to guard against losses in a stock or other asset. The put option acts like an insurance policy—it costs money, which reduces the investor's potential gains from owning the security but also reduces the risk of losing money if the security declines in value. A protective put is also known as a married put.
Breaking Down the Protective Put
Protective puts involve being long a stock and purchasing put options for that stock with a strike price that is near the underlying stock's current price or slightly out of the money. A protective put is typically used when an investor is still bullish on a stock but wishes to hedge against potential losses and uncertainty.
Profit and Loss
The maximum profit of a protective put is theoretically unlimited as the strategy involves being long on the underlying stock. If the stock keeps rising, the long stock position benefits and the bought put option isn't needed.
The maximum loss is limited to the purchase price of the underlying stock less the strike price of the put option and the premium paid. The strike price of the put option acts as a barrier where losses in the underlying stock stop. The ideal situation in a protective put is for the stock price to increase, as the investor would benefit from the long stock position. In this case, the put option will expire worthless, but the stock will have increased in value.
Take a look at my other two videos in this series, one on covered calls and one on put call parity where we learn the relationship between a protective put and being long a call option.
Covered Call Video: https://www.youtube.com/watch?v=UlC9iM2Wh7I
Put Call Parity Video: https://www.youtube.com/watch?v=LPrlfElGZJ0&t=0sLearn more about your ad choices. Visit megaphone.fm/adchoices
Investing In An Inflationary Environment!
Learn more about your ad choices. Visit megaphone.fm/adchoices
Should Companies Make Political Donations?
Companies across major sectors of the market are reassessing political donations in response to the January 6th storming of the U.S. Capitol, but it is too soon to know whether it leads to fundamental changes …
Show notes
Companies across major sectors of the market are reassessing political donations in response to the January 6th storming of the U.S. Capitol, but it is too soon to know whether it leads to fundamental changes in the way money flows between politics and business. In this video we discuss whether companies should make political donations?
Stewart Lee: Values of the Car Phone Warehouse: https://www.youtube.com/watch?v=W2firijxQOo&t=178s
Patrick's Books:
Statistics For The Trading Floor: https://amzn.to/3eerLA0
Derivatives For The Trading Floor: https://amzn.to/3cjsyPF
Corporate Finance: https://amzn.to/3fn3rvC
Patreon Page: https://www.patreon.com/PatrickBoyleOnFinance
Visit our website: www.onfinance.org
Follow Patrick on Twitter Here: https://twitter.com/PatrickEBoyle
Patrick Boyle On Finance Podcast:
Spotify: https://open.spotify.com/show/7uhrWlDvxzy9hLoW0EYf0b
Apple: https://podcasts.apple.com/us/podcast/patrick-boyle-on-finance/id1547740313
Google Podcasts: https://tinyurl.com/62862nve
Join this channel to support making this content:
https://www.youtube.com/channel/UCASM0cgfkJxQ1ICmRilfHLw/joinLearn more about your ad choices. Visit megaphone.fm/adchoices
Time Varying Volatility and GARCH in Risk Management
These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0 Check out our website http://www.onfinance.org/Follow Patrick on …
Show notes
These classes are all based on the book Trading and Pricing Financial Derivatives, available on Amazon at this link. https://amzn.to/2WIoAL0
Check out our website http://www.onfinance.org/
Follow Patrick on twitter here: https://twitter.com/PatrickEBoyle
In Todays video let's learn about time varying volatility and GARCH in risk management
Follow Patrick on Twitter Here: https://twitter.com/PatrickEBoyle
What Is Time-Varying Volatility?
Time-varying volatility refers to the changes in market volatility over different time periods. Investors may choose to study or consider volatility of an underlying security during various time periods. The use of time-varied volatility measures can influence the expectations of investments.
How Time-Varying Volatility Works
Time-varying volatility can be studied in any time-frame. Generally, volatility analysis requires mathematical modeling to generate volatility levels as one measure of the risk of an underlying security. This type of modeling generates historical volatility statistics.
What is the GARCH Process?
The generalized autoregressive conditional heteroskedasticity (GARCH) process is an econometric term developed in 1982 by Robert F. Engle, an economist and 2003 winner of the Nobel Memorial Prize for Economics, to describe an approach to estimate volatility in financial markets. There are several forms of GARCH modeling. The GARCH process is often preferred by financial modeling professionals because it provides a more real-world context than other forms when trying to predict the prices and rates of financial instruments.
Heteroskedasticity describes the irregular pattern of variation of an error term, or variable, in a statistical model. Essentially, where there is heteroskedasticity, observations do not conform to a linear pattern. Instead, they tend to cluster. The result is that the conclusions and predictive value one can draw from the model will not be reliable. GARCH is a statistical model that can be used to analyze a number of different types of financial data, for instance, macroeconomic data. Financial institutions often use this model to estimate the volatility of returns for stocks, bonds and market indices. They use the resulting information to help determine pricing and judge which assets will potentially provide higher returns, as well as to forecast the returns of current investments to help in their asset allocation, hedging, risk management and portfolio optimization decisions.Learn more about your ad choices. Visit megaphone.fm/adchoices
The Economic Effects of Russia’s Invasion of Ukraine.
Learn more about your ad choices. Visit megaphone.fm/adchoices
These are the latest 40 of 381 episodes. You’ll find older episodes in the podcast’s feed.
Similar podcasts
More Education podcasts
Is this your podcast?
Confirm it with an entry in your feed: you get a code here, add it as podcast:txt to the channel of your feed, and we check it. Your podcast is then shown as “verified” on SoundNode.